Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua.

Trusted advice. Tailored home loan solutions.

About Always Approved Capital

We’re here to guide you home. Whether you’re buying for the first time, upgrading your space, or expanding your investment portfolio, we make the mortgage process simple, supportive, and tailored to you.

0 +
Loan Products Available.
0 +
Of the Best Lenders.

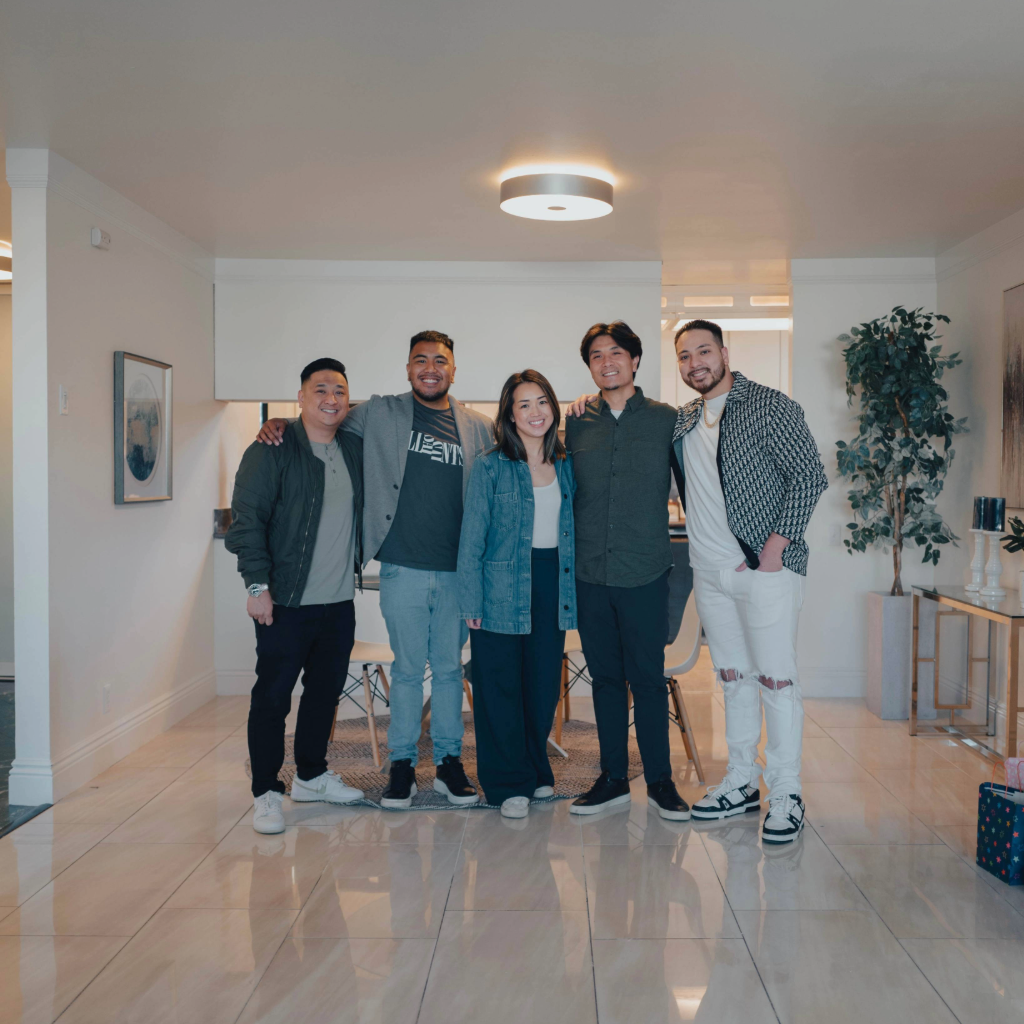
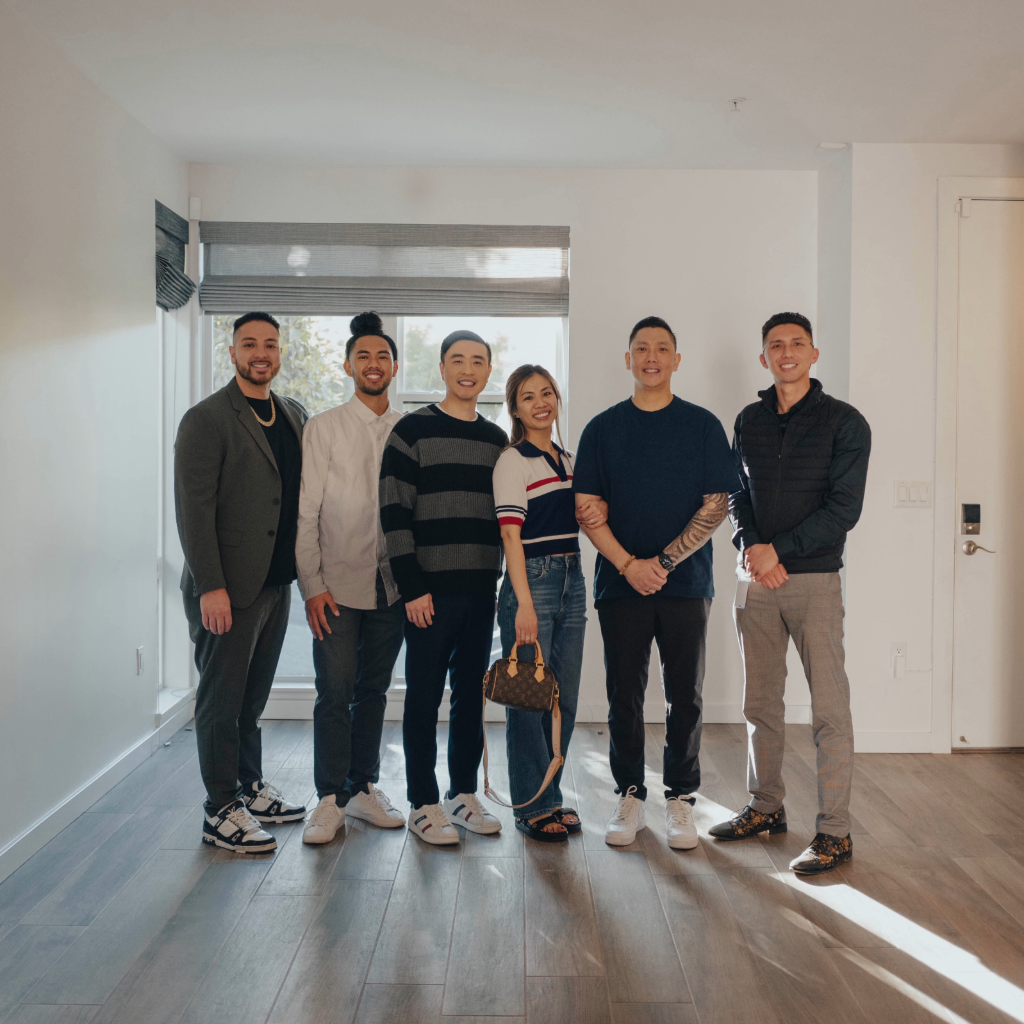
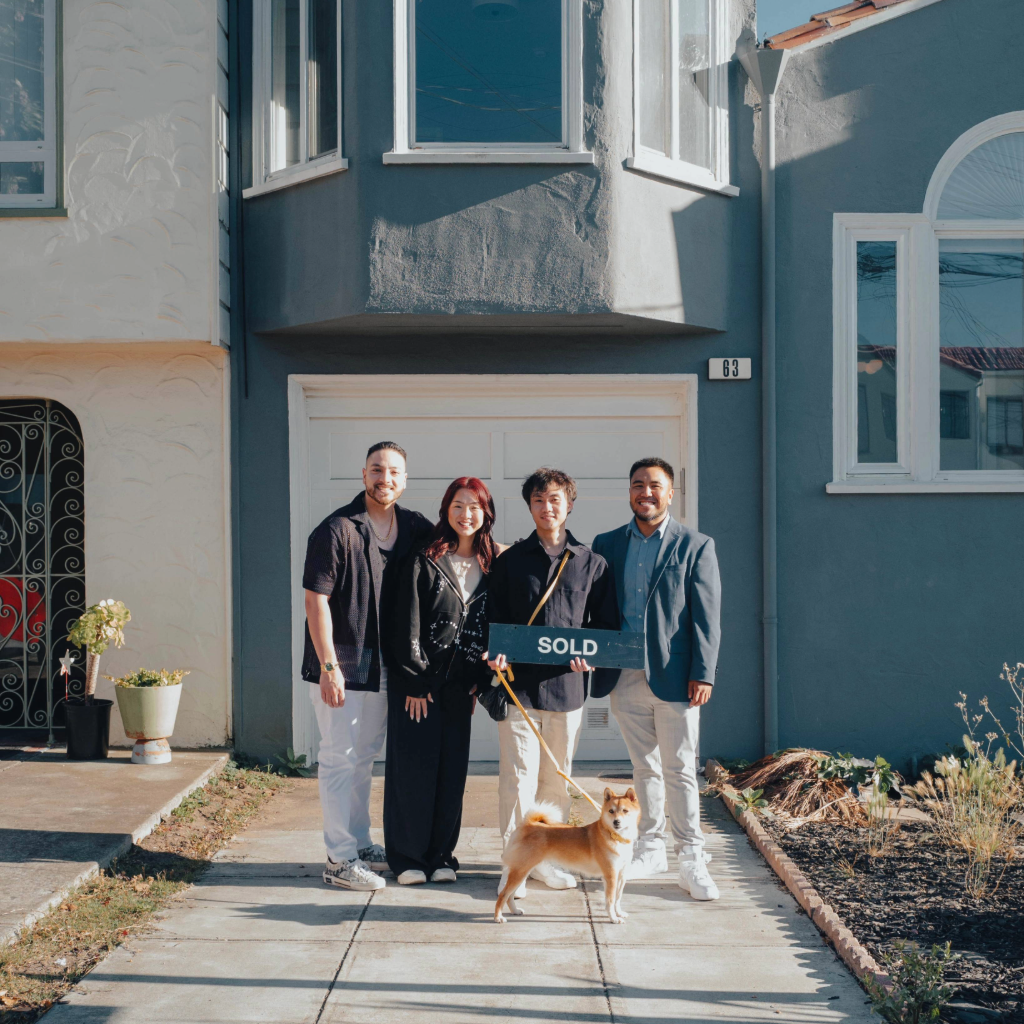
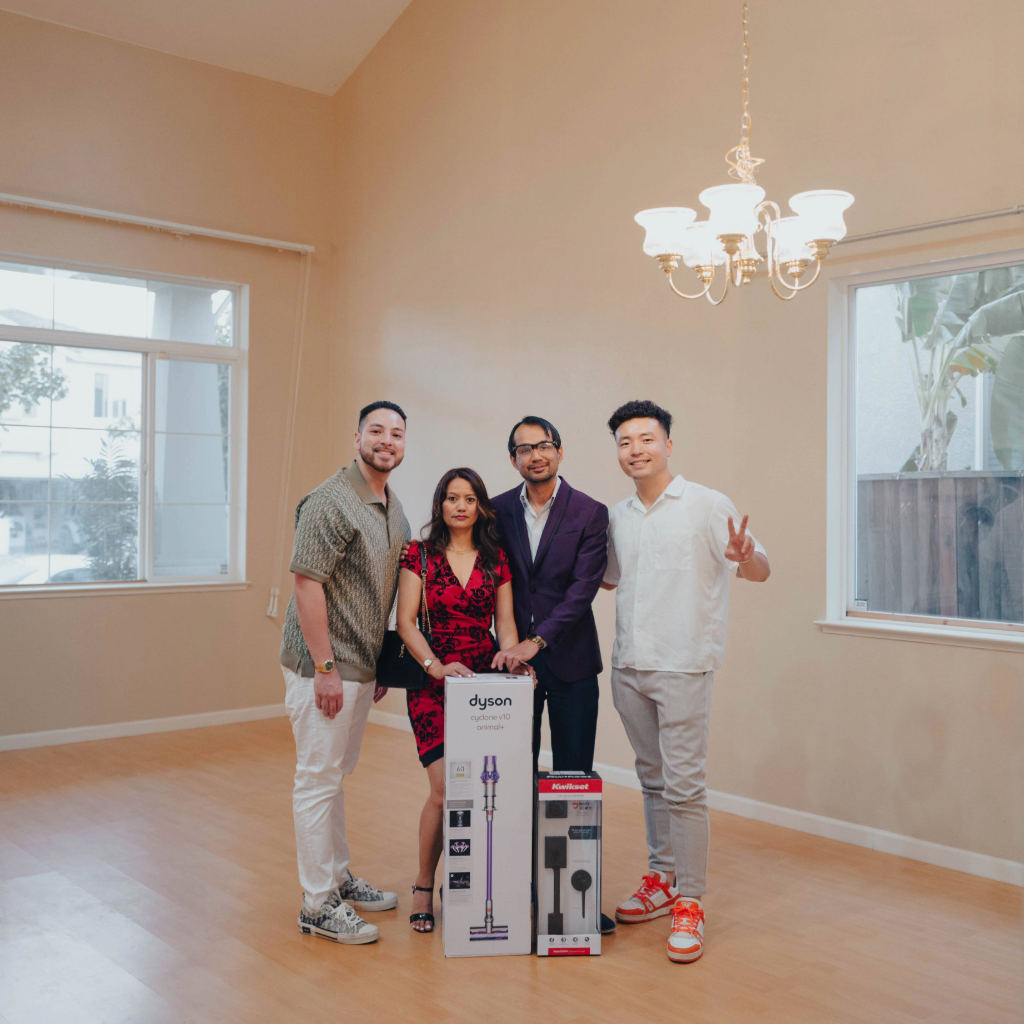
Meet Our Team

Our knowledgeable loan officers are here to walk you through any lending situation with clarity, confidence, and care.

Matthew Yu-Bahmannejad

  • Chief Loan Officer, Founder, & REALTOR®
  • NMLS #1425430

Matthew is a seasoned mortgage professional, real estate expert, and entrepreneur with a dynamic background in finance, banking, tech, and investing. He earned his degree in finance from San Jose State University and began his career at J.P. Morgan Chase Bank as a Private Banker, where he held securities licenses and specialized in investment management and advising small to medium-sized business clients.

After banking, Matthew spent six years in the tech industry, leading mid-market sales divisions at fast-growing startups. In 2020, he expanded his investment focus to include options trading—and continues to trade actively today, applying analytical discipline and market insight to manage risk and build long-term wealth.

Matthew is the founder and Chief Loan Officer of Always Approved Capital, where he works as a Mortgage Broker and loan officer. He is also a licensed REALTOR® with Coldwell Banker Los Gatos, and an active real estate investor in the Bay Area. His investment strategy centers on distressed properties—acquiring, renovating, and selling them for profit.

Outside of work, Matthew enjoys being a dedicated dog dad to his mini golden doodle, weight training, riding his motorcycle, trading the markets, and working on his collection of Porsches. He’s also an avid foodie who loves discovering new restaurants with his loved ones—bringing the same drive and curiosity to life as he does to every business venture.

Damian Rangel

  • Senior Loan Officer & REALTOR®
  • NMLS #1839850

Spanish Speaker

Damian Rangel brings more than 20 years of real estate experience and a deep commitment to helping individuals and families achieve their homeownership goals. As the son of immigrants, he understands firsthand the value of hard work, opportunity, and building a better future for one’s family.

Fluent in both English and Spanish, Damian takes pride in making the loan process clear and approachable, especially for clients who may feel overwhelmed by financing or are purchasing a home for the first time. His extensive real estate background gives him a unique understanding of the entire home-buying process, allowing him to guide clients with knowledge, patience, and personal attention.

For Damian, every loan is an opportunity to help someone take an important step toward financial stability, prosperity, and the American dream of homeownership.

David Cao

  • Senior Loan Officer & REALTOR®
  • NMLS #634344

David is a real estate and mortgage professional who brings a hands-on perspective to helping clients navigate homeownership, financing, and real estate investing. As both a licensed REALTOR® and Mortgage Loan Officer, David understands that the right financing strategy goes beyond simply finding a competitive rate—it should complement a client’s real estate goals and overall financial picture.

Based in the Bay Area, David has built his real estate business working with first-time homebuyers, move-up buyers, sellers, and investors throughout Silicon Valley and surrounding communities. His experience on the real estate side gives him a unique understanding of what it takes to get an offer accepted, navigate appraisals and contingencies, structure competitive financing, and keep a transaction moving toward a successful closing.

David is also an active real estate investor with firsthand experience owning and managing rental properties, building ADUs, and renovating homes. That experience allows him to approach lending from an investor’s perspective as well as a homeowner’s—helping clients evaluate opportunities, understand their financing options, and make informed decisions with both their immediate needs and long-term goals in mind.

What David values most is being a trusted resource for his clients. Rather than viewing a mortgage as a single transaction, he focuses on building long-term relationships and helping clients understand how real estate and financing can work together as part of a broader wealth-building strategy.

Outside of work, David enjoys spending time with his wife and children, working on home improvement and real estate projects, staying active, traveling, and exploring great food throughout the Bay Area.

Peter Ly

  • Senior Loan Officer & REALTOR®
  • NMLS #2563674

Peter brings a unique advantage to the mortgage process: insight from both sides of the transaction. As both a seasoned real estate agent and a licensed loan officer, he helps clients navigate home financing with clarity, efficiency, and strategic guidance. With over a decade of experience in business and real estate, Peter anticipates challenges before they arise—bridging the gap between agents, lenders, and clients to keep transactions moving forward.

Whether clients are buying, refinancing, or investing, Peter offers practical advice, tailored loan solutions, and clear communication every step of the way. His dual expertise allows him to provide a comprehensive perspective that ensures smoother, more successful outcomes for his clients.

Outside of work, Peter enjoys spending time with his family, training in Brazilian jiu-jitsu, and cycling. He rides regularly and completes a 100-mile century ride each year—bringing the same endurance, discipline, and focus to his professional life as he does to his personal passions.

Dewey Vuong

  • Senior Loan Officer & REALTOR®
  • NMLS #2568842

Dewey brings local insight and a deep understanding of the Bay Area’s diverse real estate landscape. Since 2018, he’s helped over 100 buyers and sellers navigate competitive markets with smart strategy, strong negotiation, and clear guidance.

A proud CSU East Bay graduate, Dewey stays active in the real estate community through leadership roles with AREAA and YPN, and by mentoring new agents. With a strong grasp of both real estate and financing, he’s committed to helping clients make confident, informed decisions from start to finish.

Outside of work, Dewey enjoys family camping trips, cycling Bay Area trails, and supporting local businesses—especially the ones with great food.

Jimmy Nguyen

  • Senior Loan Officer
  • NMLS #2716655

Vietnamese Speaker

Jimmy is a Bay Area native who has spent well over a decade living throughout Southern California. From the Inland Empire and Orange County to San Diego, he knows Southern California like the back of his hand. Whether his clients are looking for the right neighborhood, the best coffee shops, beaches, or local eats—or simply need someone who understands the local market—Jimmy is always ready to help.
Fluent in Vietnamese, Jimmy is also able to serve Vietnamese-speaking clients and families throughout California. As a registered nurse currently pursuing his advanced degree, he understands the importance of accuracy, attention to detail, clear communication, and exceptional customer service. He brings that same level of care, precision, and responsibility to every client he helps with their home financing.

Outside of work, Jimmy is a proud #girldad to two amazing daughters and a dog dad to a long-haired dachshund. On his days off, he can usually be found at the boxing gym, where he clears his head and stays sharp.

Johnson La

  • Senior Loan Officer & REALTOR®
  • NMLS #2153149

Johnson is a Bay Area native who has called San Francisco home for more than 30 years. As a proud SFUSD graduate and longtime member of the community, he brings firsthand knowledge of the neighborhoods, people, and character that make San Francisco and the greater Bay Area unique.

Giving back to his community has always been an important part of Johnson’s life. From helping lead Galileo Academy’s football team to a city championship as an assistant coach to serving as an SFUSD school bus driver, he has always believed in showing up, working hard, and looking out for others. He brings those same values to real estate, providing his clients with local expertise, integrity, responsiveness, and a personal approach to buying, selling, and investing.

Outside of real estate, Johnson enjoys spending time with his wife, their dog, and two cats. He also enjoys trying new foods, discovering local restaurants, and exploring new hobbies.

Our Mortgage Solutions

The most popular mortgage loan out there. Ideal for someone with 720+ credit score with down payment as little as 3% down. Conventional loans work for your primary residence, second home, or investment property.

A great option for borrowers who have a credit score of 500 – 700 and are looking to put a smaller down payment. You can only use this for your primary residence and can only have 1 FHA loan at a time

Are loans larger than the maximum high-balance conventional limit. They require at least 10.01% down payment, have a lower debt-to-income ratio limit, require verification of rent, and require reserves.

Loans for active, former (honorably discharged) military members or their spouses if the military member died in the line of duty. VA loans come with lower rates, no mortgage insurance and you don’t have to put any money down in some cases.

The most popular loan for business owners who have “too many write-offs.” Since conventional loans use net income for self-employed borrowers, plenty do not qualify for a mortgage. A bank statement loan is a great option because it will take an average of the deposits into your business account over 12 or 24 months and use that as income vs tax-returns.

These loans are for investment properties only and can be for single units all the way up to 32 units. The lender determines eligibility by taking the total rent(s) from the investment property and dividing it by your total monthly mortgage payment. Depending on the ratio will determine your eligibility and interest rate. These loans typically have a prepayment penalty from 0-5 years. The lower the years, the higher the rate.

These loans are for borrowers who need creative financing. These loans are great for fix & flip properties, fix & hold properties, gap funding, ground-up construction, and many more! We can find you a lender that will help finance the purchase of the property and typically finance 100% of the rehab (funds needed remodeling).

These loans are intended for borrowers who are looking for financing to buy land and/or also finance the construction costs. A great solution to create your dream home.


These loans are great for individuals who do not have proof of income and typically require a higher down payment of at least 15%.

These loans are great for business owners who have “too many” write-offs, but can provide a profit-loss statement from their CPA.

These loans are for condo communities that can not secure conventional financing and have been deemed as non-warrantable. A condo can be considered non-warrantable because of repairs, SB-326 issues, lack of reserves, lack of insurance coverage, litigations and lawsuits, and much more.

These loans are for borrowers who do not have a social security number and only an ITIN.

Have more questions?

FHA Loans

Federal Housing Administration (FHA) loans are government-backed mortgages designed to help first-time homebuyers and those with lower credit scores or limited down payment savings.
With easier qualification requirements, FHA loans are a popular choice for making homeownership accessible to more people.

Flexible Debt-to-Income Ratios

Easier approval for those with higher debt levels.

Flexible Debt-to-Income Ratios

Easier approval for those with higher debt levels.

Flexible Debt-to-Income Ratios

Easier approval for those with higher debt levels.

Contact Us

We’re Here to Help – Reach Out Anytime

Phone

415.577.2057

Email

hello@alwaysapprovedcapital.com

Send us a message

"*" indicates required fields

FAQs

Common questions about the application process, loan types, and how Always Approved Capital can help.

No, some programs allow for as little as 3% for down payment.

There are no costs or fees to get started. You are not obligated to work with us even if you started with us.

It’s difficult to provide exact closing costs before an offer is accepted, and here’s why: closing costs are determined by various third-party vendors involved in the real estate transaction—and in many cases, you’re not allowed to choose these vendors. These fees and vendors include, but are not limited to: escrow, title, title insurance, appraiser, credit reports, county transfer tax, city transfer tax (if applicable), recording fees, notary, HOA (if applicable), homeowner’s insurance, property taxes (if impounded/escrowed), pro-rated interest, and more.

Since we don’t yet know which vendors will be involved or what their specific fees will be, it’s impossible to give an exact figure in advance. Additionally, some of these costs may be paid by the seller or split between buyer and seller.

On average, closing costs typically range from 1.5% to 2.5% of the purchase price.

Yes, because we fully underwrite your file from the start, this allows us to streamline the lending process. Our production volume also gives us priority and faster turnaround times than other brokers/loan officers.

Reach out to your loan officer to get started on the mortgage application process, or simply click the “Apply for Mortgage” on the top right of this page.

Depending on your income source, typically you’ll need your two most recent pay stubs, W-2s from the last two years, a Driver’s License/ID, and your two most recent bank or brokerage statements.

We successfully help borrowers get qualified without a two-year work history.

Most lenders will tell you that your pre-approval is valid for 90 to 120 days, as that’s when the credit report expires. In theory, your pre-approval remains valid as long as your income stays the same, your debts/loans don’t increase, and the interest rate remains unchanged.

Unlike most mortgage brokers, lenders, and banks, we offer “soft checks” as an option for all our borrowers. A hard pull will be required when we submit to the lender, typically occurring once the offer is accepted.

Points are a one-time fee paid at closing, calculated as a percentage of your loan amount. For example, 0.75 points on a $900,000 loan equals $6,750. Buyers often pay points to get a lower interest rate, but it’s not always worth it—ask your loan officer if it makes sense for your situation.
We can lock in your rate once the offer is accepted and we have a fully executed purchase agreement from both the seller and the buyer (you).
Interest rates are specific to each borrower, meaning what you qualify for may differ significantly from someone else. Key factors that influence your interest rate include your credit score, down payment amount, loan size, the city and county of your purchase, property type (e.g., single-family home vs. condo), combined income, citizenship status, whether you’re a first-time buyer, and many other variables.

Interest rates change daily, and sometimes as much as 2 or 3 times intra-day. Think of interest rates just like the stock market. It fluctuates based on the bond market.

To avoid mortgage insurance, you’ll need to put down at least 20% for conventional loans. FHA loans require mortgage insurance regardless of your down payment. Most jumbo loans do not include mortgage insurance.

Yes, all lenders require homeowner’s insurance if you are to take out a loan.

Since we work directly with over 55 lenders, there’s a strong likelihood that we have a program that suits your needs regardless of your credit score.

We offer programs like the Bank Statement Loan that do not require tax returns and do not look at your write-offs.

We have solutions for that, as well as programs that don’t require tax returns.

Yes, we have many lenders that will work with your citizenship status.

Have more questions?

Guiding You Home, One Loan at a Time

We’re here to answer your questions and provide expert advice. Reach out to us anytime—we’d love to hear from you!